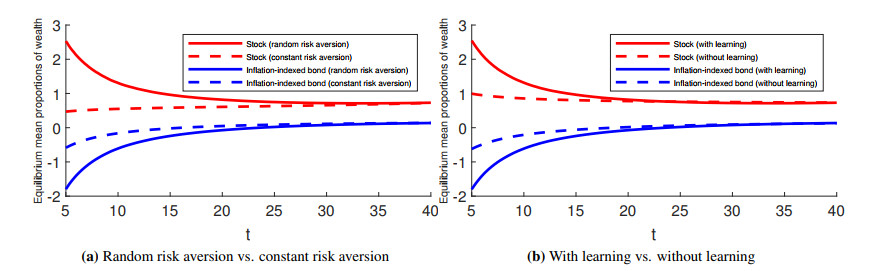
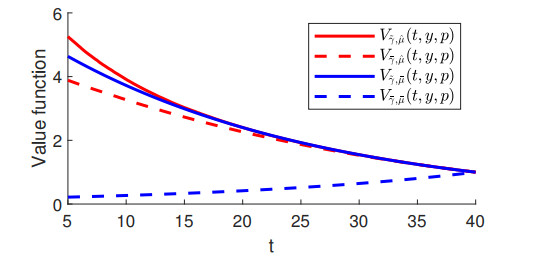
This paper investigated the equilibrium investment strategy for a defined contribution (DC) pension plan that incorporates random risk aversion and stock return predictability. The financial market consists of a risk-free asset, an inflation-indexed bond, and a stock, where the expected stock return is driven by an unobservable mean-reverting predictor. By filtering techniques, a DC member dynamically learns and updates the estimation of this unobservable predictor based on the observations. Different from previous studies that consider only random risk aversion and resort to a system of ordinary differential equations (ODEs), this paper further incorporated stock return predictability and characterized the equilibrium strategy as a system of partial differential equations (PDEs). In the case of power utility, we derived the semi-closed form of the equilibrium investment strategy as the solution of a PDE system, and verified the existence of the solution by the Banach fixed-point theorem. Rigorous analysis showed that ignoring either random risk aversion or stock return predictability leads to welfare loss. Numerical analysis confirmed the welfare loss.
Citation: Jiaqi Qian, Jiaming Su, Yongqiao Wang. Dynamic learning for a DC pension plan with random risk aversion[J]. Journal of Industrial and Management Optimization, 2026, 22(9): 4599-4626. doi: 10.3934/jimo.2026160
This paper investigated the equilibrium investment strategy for a defined contribution (DC) pension plan that incorporates random risk aversion and stock return predictability. The financial market consists of a risk-free asset, an inflation-indexed bond, and a stock, where the expected stock return is driven by an unobservable mean-reverting predictor. By filtering techniques, a DC member dynamically learns and updates the estimation of this unobservable predictor based on the observations. Different from previous studies that consider only random risk aversion and resort to a system of ordinary differential equations (ODEs), this paper further incorporated stock return predictability and characterized the equilibrium strategy as a system of partial differential equations (PDEs). In the case of power utility, we derived the semi-closed form of the equilibrium investment strategy as the solution of a PDE system, and verified the existence of the solution by the Banach fixed-point theorem. Rigorous analysis showed that ignoring either random risk aversion or stock return predictability leads to welfare loss. Numerical analysis confirmed the welfare loss.

| [1] |
J. Boulier, S. Huang, G. Taillard, Optimal management under stochastic interest rates: the case of a protected defined contribution pension fund, Insur. Math. Econ., 28 (2001), 173–189. https://doi.org/10.1016/s0167-6687(00)00073-1 doi: 10.1016/s0167-6687(00)00073-1

|
| [2] | N. Han, M. Hung, Optimal asset allocation for DC pension plans under inflation, Insur. Math. Econ., 51 (2012): 172–181. https://doi.org/10.1016/j.insmatheco.2012.03.003 |
| [3] |
G. Guan, Z. Liang, Optimal management of DC pension plan in a stochastic interest rate and stochastic volatility framework, Insur. Math. Econ., 57 (2014), 58–66. https://doi.org/10.1016/j.insmatheco.2014.05.004 doi: 10.1016/j.insmatheco.2014.05.004
|
| [4] |
T. Björk, A. Murgoci, X. Zhou, Mean–variance portfolio optimization with state-dependent risk aversion, Math. Finance, 24 (2014), 1–24. https://doi.org/10.1111/j.1467-9965.2011.00515.x doi: 10.1111/j.1467-9965.2011.00515.x
|
| [5] |
T. Björk, M. Khapko, A. Murgoci, On time-inconsistent stochastic control in continuous time, Finance Stoch., 21 (2017), 331–360. https://doi.org/10.1007/s00780-017-0327-5 doi: 10.1007/s00780-017-0327-5
|
| [6] |
H. Wu, Y. Zeng, Equilibrium investment strategy for defined-contribution pension schemes with generalized mean–variance criterion and mortality risk, Insur. Math. Econ., 64 (2015), 396–408. https://doi.org/10.1016/j.insmatheco.2015.07.007 doi: 10.1016/j.insmatheco.2015.07.007
|
| [7] |
L. Zhang, D. Li, Y. Lai, Equilibrium investment strategy for a defined contribution pension plan under stochastic interest rate and stochastic volatility, J. Comput. Appl. Math., 368 (2020), 112536. https://doi.org/10.1016/j.cam.2019.112536 doi: 10.1016/j.cam.2019.112536
|
| [8] |
P. Wang, Y. Shen, L. Zhang, Y. Kang, Equilibrium investment strategy for a DC pension plan with learning about stock return predictability, Insur. Math. Econ., 100 (2021), 384–407. https://doi.org/10.1016/j.insmatheco.2021.07.001 doi: 10.1016/j.insmatheco.2021.07.001
|
| [9] | C. M. Glória, J. C. Dias, J. P. Ruas, Robust strategy for a member of defined contribution pension plan when asset prices can jump, Scand. Actuar. J., (2026), 1–26. https://doi.org/10.1080/03461238.2026.2667958 |
| [10] |
L. Zhang, P. Wang, Y. Shen, Time-consistent investment strategy for a DC pension plan with the return of premiums clause and mispricing, Quant. Finance, 25 (2025), 117–141. https://doi.org/10.1080/14697688.2024.2445853 doi: 10.1080/14697688.2024.2445853
|
| [11] |
S. Desmettre, M. Steffensen, Equilibrium investment with random risk aversion, Math. Finance, 33 (2023), 946–975. https://doi.org/10.1111/mafi.12394 doi: 10.1111/mafi.12394
|
| [12] |
L. Wang, B. Jia, Equilibrium investment strategies for a defined contribution pension plan with random risk aversion, Insur. Math. Econ., 125 (2025), 103140. https://doi.org/10.1016/j.insmatheco.2025.103140 doi: 10.1016/j.insmatheco.2025.103140
|
| [13] |
T. Bollerslev, M. Gibson, H. Zhou, Dynamic estimation of volatility risk premia and investor risk aversion from option-implied and realized volatilities, J. Econom., 160 (2011), 235–245. https://doi.org/10.1016/j.jeconom.2010.03.033 doi: 10.1016/j.jeconom.2010.03.033
|
| [14] |
J. Burgaard, M. Steffensen, Eliciting risk preferences and elasticity of substitution, Decis. Anal., 17 (2020), 314–329. https://doi.org/10.1287/deca.2020.0415 doi: 10.1287/deca.2020.0415
|
| [15] |
G. Alserda, B. Dellaert, L. Swinkels, F. van der Lecq, Individual pension risk preference elicitation and collective asset allocation with heterogeneity, J. Bank. Financ., 101 (2019), 206–225. https://doi.org/10.1016/j.jbankfin.2019.02.014 doi: 10.1016/j.jbankfin.2019.02.014
|
| [16] |
Y. Hu, H. Jin, X. Zhou, Time-inconsistent stochastic linear–quadratic control, SIAM J. Control Optim., 50 (2012), 1548–1572. https://doi.org/10.1137/110853960 doi: 10.1137/110853960
|
| [17] |
S. Li, C. Luong, F. Angkola, Y. Wu, Optimal asset portfolio with stochastic volatility under the mean-variance utility with state-dependent risk aversion, J. Ind. Manag. Optim., 12 (2016), 1521–1533. https://doi.org/10.3934/jimo.2016.12.1521 doi: 10.3934/jimo.2016.12.1521
|
| [18] |
J. Sun, H. Li, Y. Zeng, Precommitment and equilibrium investment strategies for defined contribution pension plans under a jump–diffusion model, Insur. Math. Econ., 67 (2016), 158–172. https://doi.org/10.1016/j.insmatheco.2016.01.005 doi: 10.1016/j.insmatheco.2016.01.005
|
| [19] |
L. Wang, Z. Chen, P. Yang, Robust equilibrium control-measure policy for a DC pension plan with state-dependent risk aversion under mean-variance criterion, J. Ind. Manag. Optim., 17 (2021), 1203–1233. https://doi.org/10.3934/jimo.2020018 doi: 10.3934/jimo.2020018
|
| [20] |
J. Campbell, R. Shiller, The dividend-price ratio and expectations of future dividends and discount factors, Rev. Financ. Stud., 1 (1986), 195–228. https://doi.org/10.1093/rfs/1.3.195 doi: 10.1093/rfs/1.3.195
|
| [21] |
E. Fama, K. French, Permanent and temporary components of stock prices, J. Polit. Econ., 96 (1988), 246–273. https://doi.org/10.1086/261535 doi: 10.1086/261535
|
| [22] | E. Fama, K. French, Business conditions and expected returns on stocks and bonds. J. Financ. Econ., 25 (1989), 23–49. https://doi.org/10.1016/0304-405X(89)90095-0 |
| [23] |
J. Campbell, L. Viceira, Consumption and portfolio decisions when expected returns are time varying, Q. J. Econ., 114 (1999), 433–495. https://doi.org/10.1162/003355399556043 doi: 10.1162/003355399556043
|
| [24] | H. Pham, M. Quenez, Optimal portfolio in partially observed stochastic volatility models. Ann. Appl. Probab., 11 (2001), 210–238. https://doi.org/10.1214/aoap/998926991 |
| [25] |
Y. Xia, Learning about predictability: the effects of parameter uncertainty on dynamic asset allocation, J. Finance, 56 (2001), 205–246. https://doi.org/10.1111/0022-1082.00323 doi: 10.1111/0022-1082.00323
|
| [26] |
J. Cochrane, The dog that did not bark: a defense of return predictability, Rev. Financ. Stud., 21 (2008), 1533–1575. https://doi.org/10.1093/rfs/hhm046 doi: 10.1093/rfs/hhm046
|
| [27] |
P. Wang, L. Zhang, Z. Li, Asset allocation for a DC pension plan with learning about stock return predictability, J. Ind. Manag. Optim., 18 (2022), 3847–3877. https://doi.org/10.3934/jimo.2021138 doi: 10.3934/jimo.2021138
|
| [28] | P. Wang, Z. Li, L. Zhang, Optimal investment strategy for a DC pension with incomplete information and ambiguity aversion, Oper. Res. Manag. Sci., 31 (2022), 125. |
| [29] |
X. Peng, L. Luo, Optimal investment strategy for DC pension with mean-weighted variance-CVaR criterion under partial information, Insur. Math. Econ., 120 (2025), 302–324. https://doi.org/10.1016/j.insmatheco.2024.12.006 doi: 10.1016/j.insmatheco.2024.12.006
|
| [30] | X. Peng, S. Fan, Asset allocation for a DC pension plan with dynamic attention. Finance Res. Lett., 82 (2025), 107513. https://doi.org/10.1016/j.frl.2025.107513 |
| [31] | S. Gao, J. Guo, X. Liang, Bayesian adaptive portfolio optimization for DC pension plans. Insur. Math. Econ., 122 (2025), 262–274. https://doi.org/10.1016/j.insmatheco.2025.04.001 |
| [32] |
J. Fouque, A. Papanicolaou, R. Sircar, Filtering and portfolio optimization with stochastic unobserved drift in asset returns, Commun. Math. Sci., 13 (2015), 935–953. https://doi.org/10.4310/CMS.2015.v13.n4.a5 doi: 10.4310/CMS.2015.v13.n4.a5
|
| [33] |
X. Peng, B. Li. Optimal investment, consumption and life insurance purchase with learning about return predictability, Insur. Math. Econ., 113 (2023), 70–95. https://doi.org/10.1016/j.insmatheco.2023.07.005 doi: 10.1016/j.insmatheco.2023.07.005
|
| [34] |
N. Branger, L. Larsen, C. Munk, Robust portfolio choice with ambiguity and learning about return predictability, J. Bank. Financ., 37 (2013), 1397–1411. https://doi.org/10.1016/j.jbankfin.2012.05.009 doi: 10.1016/j.jbankfin.2012.05.009
|
| [35] |
M. Escobar, S. Ferrando, A. Rubtsov, Portfolio choice with stochastic interest rates and learning about stock return predictability, Int. Rev. Econ. Financ., 41 (2016), 347–370. https://doi.org/10.1016/j.iref.2015.07.003 doi: 10.1016/j.iref.2015.07.003
|
| [36] |
N. Wang, T. Siu, Investment–consumption optimization with transaction cost and learning about return predictability, Eur. J. Oper. Res., 318 (2024), 877–891. https://doi.org/10.1016/j.ejor.2024.06.024 doi: 10.1016/j.ejor.2024.06.024
|
| [37] |
S. Altay, K. Colaneri, E. Zehra, F. Eva, Filtering market signals: dynamic asset allocation with momentum and hidden mean reversion, Quant. Finance, 26 (2026), 593–613. https://doi.org/10.1080/14697688.2026.2627261 doi: 10.1080/14697688.2026.2627261
|
| [38] |
F. Chen, K. Ji, X. Peng, Optimal investment and reinsurance strategy for an insurer with loss aversion under partial information, Syst. Eng. Theory Pract., 44 (2024), 932–946. https://doi.org/10.12011/SETP2023-0267 doi: 10.12011/SETP2023-0267
|
| [39] | C. Ceci, K. Colaneri, Portfolio and reinsurance optimization under unknown market price of risk. Quant. Finance, 25 (2025), 217–229. https://doi.org/10.1080/14697688.2024.2384392 |
| [40] |
T. Siu, A BSDE approach to risk-based asset allocation of pension funds with regime switching, Ann. Oper. Res., 201 (2012), 449–473. https://doi.org/10.1007/s10479-012-1211-5 doi: 10.1007/s10479-012-1211-5
|
| [41] |
X. Peng, H. Zhou, L. Luo, Time-consistent investment strategy for a DC pension plan with hidden Markov regime switching, J. Comput. Appl. Math., 425 (2023), 115058. https://doi.org/10.1016/j.cam.2023.115058 doi: 10.1016/j.cam.2023.115058
|
| [42] |
L. Xie, D. Li, L. Qian, L. Chen, Z. Yang, Optimal investment strategy for an insurer with partial information in capital and insurance markets, J. Ind. Manag. Optim., 19 (2023), 5249–5271. https://doi.org/10.3934/jimo.2022171. doi: 10.3934/jimo.2022171
|
| [43] |
L. Xie, L. Qian, L. Chen, L. Yang, D. Li, Optimal asset allocation for pooled annuity under ambiguity aversion and partial information, J. Ind. Manag. Optim., 21 (2025), 6794–6827. https://doi.org/10.3934/jimo.2025149 doi: 10.3934/jimo.2025149
|
| [44] | R. Liptser, A. Shiryaev, Statistics of Random Processes, Springer-Verlag, Berlin, 2001. https://doi.org/10.1007/978-3-662-10028-8 |
| [45] |
M. Meyries, R. Schnaubelt, Interpolation, embeddings and traces of anisotropic fractional sobolev spaces with temporal weights, J. Funct. Anal., 262 (2012), 1200–1229. https://doi.org/10.1016/j.jfa.2011.11.001 doi: 10.1016/j.jfa.2011.11.001
|
| [46] | N. Lindemulder, Maximal regularity with weights for parabolic problems with inhomogeneous boundary conditions. J. Evol. Equ., 20 (2019), 59–108. https://doi.org/10.1007/s00028-019-00515-7 |
| [47] | J. Prüss, G. Simonett, Maximal regularity for evolution equations in weighted L$_p$-spaces, Arch. Math., 82 (2004), 415–431. https://doi.org/10.1007/s00013-004-0585-2 |
| [48] | X. Mao, Stochastic Differential Equations and Applications, Elsevier, 2007. https://doi.org/10.1533/9780857099402 |
| [49] |
J. Liu, Portfolio selection in stochastic environments, Rev. Financ. Stud., 20 (2007), 1–39. https://doi.org/10.1093/rfs/hhl001 doi: 10.1093/rfs/hhl001
|
 jimo-22-09-160-s001.pdf |
 |
Figures(7) / Tables(1)
Jiaqi Qian, Jiaming Su, Yongqiao Wang. Dynamic learning for a DC pension plan with random risk aversion[J]. Journal of Industrial and Management Optimization, 2026, 22(9): 4599-4626. doi: 10.3934/jimo.2026160



 DownLoad: