We study moment-equilibrium transitions in a stochastic logistic difference equation and apply the results to financial credit adjustment. Assuming four lognormal-form input moments, preservation of the mean and variance yields two explicit growth branches and an exact admissibility bound linking input dispersion with multiplicative noise variability. Both real nondegenerate branches lie below the deterministic first period-doubling boundary. An exact variance correction also connects the stochastic mean response to the deterministic logistic map. For the financial application, we use rolling 10 year windows of U.S. broker-dealer customer receivables relative to equity capital. All eligible estimated growth coefficients based on the data lie closer to the lower equilibrium branch, while discrepancies reveal departures from this benchmark around periods of financial disruption. The results connect moment equilibrium of the stochastic model and deterministic transition boundaries with observed financial adjustment, providing a model-based interpretation of these changes without establishing financial chaos.
Citation: Yunihan Wang, Haiyan Wang. Moment equilibrium and dynamical transitions in a stochastic logistic model: a financial application[J]. Big Data and Information Analytics, 2026, 10: 374-390. doi: 10.3934/bdia.2026019
We study moment-equilibrium transitions in a stochastic logistic difference equation and apply the results to financial credit adjustment. Assuming four lognormal-form input moments, preservation of the mean and variance yields two explicit growth branches and an exact admissibility bound linking input dispersion with multiplicative noise variability. Both real nondegenerate branches lie below the deterministic first period-doubling boundary. An exact variance correction also connects the stochastic mean response to the deterministic logistic map. For the financial application, we use rolling 10 year windows of U.S. broker-dealer customer receivables relative to equity capital. All eligible estimated growth coefficients based on the data lie closer to the lower equilibrium branch, while discrepancies reveal departures from this benchmark around periods of financial disruption. The results connect moment equilibrium of the stochastic model and deterministic transition boundaries with observed financial adjustment, providing a model-based interpretation of these changes without establishing financial chaos.

| [1] |
May RM, (1976) Simple mathematical models with very complicated dynamics. Nature 261: 459–467. https://doi.org/10.1038/261459a0 doi: 10.1038/261459a0
|
| [2] |
Hsieh DA, (1991) Chaos and nonlinear dynamics: Application to financial markets. J Finance 46: 1839–1877. https://doi.org/10.1111/j.1540-6261.1991.tb04646.x doi: 10.1111/j.1540-6261.1991.tb04646.x
|
| [3] |
Brock WA, Hommes CH, (1998) Heterogeneous beliefs and routes to chaos in a simple asset pricing model. J Econ Dyn Control 22: 1235–1274. https://doi.org/10.1016/S0165-1889(98)00011-6 doi: 10.1016/S0165-1889(98)00011-6
|
| [4] |
Tarasova VV, Tarasov VE, (2017) Logistic map with memory from economic model. Chaos Solitons Fractals 95: 84–91. https://doi.org/10.1016/j.chaos.2016.12.012 doi: 10.1016/j.chaos.2016.12.012
|
| [5] |
Shreve SE, (2004) Stochastic Calculus for Finance Ⅰ: The Binomial Asset Pricing Model, Springer, New York. https://doi.org/10.1007/978-0-387-22527-2 |
| [6] |
Shreve SE, (2004) Stochastic Calculus for Finance Ⅱ: Continuous-Time Models, Springer, New York. |
| [7] |
Schreiber SJ, (2012) Persistence for stochastic difference equations: A mini-review. J Differ Equations Appl 18: 1381–1403. https://doi.org/10.1080/10236198.2011.628662 doi: 10.1080/10236198.2011.628662
|
| [8] |
Wang H, (2025) Equilibrium analysis of discrete stochastic population models with gamma distribution. Math Biosci 381: 109398. https://doi.org/10.1016/j.mbs.2025.109398 doi: 10.1016/j.mbs.2025.109398
|
| [9] |
Wang H, Wang Y, (2025) Detecting transitions from steady states to chaos with gamma distribution. Int J Bifurcation Chaos 35: 2550163. https://doi.org/10.1142/S0218127425501639 doi: 10.1142/S0218127425501639
|
| [10] |
Wang H, Wang E, (2026) Stability and bifurcation of difference equations from stochastic logistic models. Math Biosci Eng 23: 449–473. https://doi.org/10.3934/mbe.2026018 doi: 10.3934/mbe.2026018
|
| [11] |
Yang Y, Han X, (2027) Equilibrium and bifurcation analysis of a stochastic logistic difference equation with additive noise. Discrete Contin Dyn Syst S, 33: 116–138. https://doi.org/10.3934/dcdss.2026151 doi: 10.3934/dcdss.2026151
|
| [12] |
Yang Y, Han X, (2027) Gamma moment-closure and noise-induced saddle-node bifurcation in a stochastic logistic difference equation. Discrete Contin Dyn Syst S 33: 420–452. https://doi.org/10.3934/dcdss.2026173 doi: 10.3934/dcdss.2026173
|
| [13] |
Stutzer MJ, (1980) Chaotic dynamics and bifurcation in a macro model. J Econ Dyn Control 2: 353–376. https://doi.org/10.1016/0165-1889(80)90070-6 doi: 10.1016/0165-1889(80)90070-6
|
| [14] |
Federal Reserve Bank of St. Louis, Numerical Tables for BOGZ1FL663067003Q and BOGZ1FL665080003Q. Available from: https://fred.stlouisfed.org/data/BOGZ1FL663067003Q; https://fred.stlouisfed.org/data/BOGZ1FL665080003Q |
| [15] |
Johnson NL, Kotz S, Balakrishnan N, (1994) Continuous Univariate Distributions, Wiley, New York. |
Figures(4) / Tables(2)

Yunihan Wang, Haiyan Wang. Moment equilibrium and dynamical transitions in a stochastic logistic model: a financial application[J]. Big Data and Information Analytics, 2026, 10: 374-390. doi: 10.3934/bdia.2026019

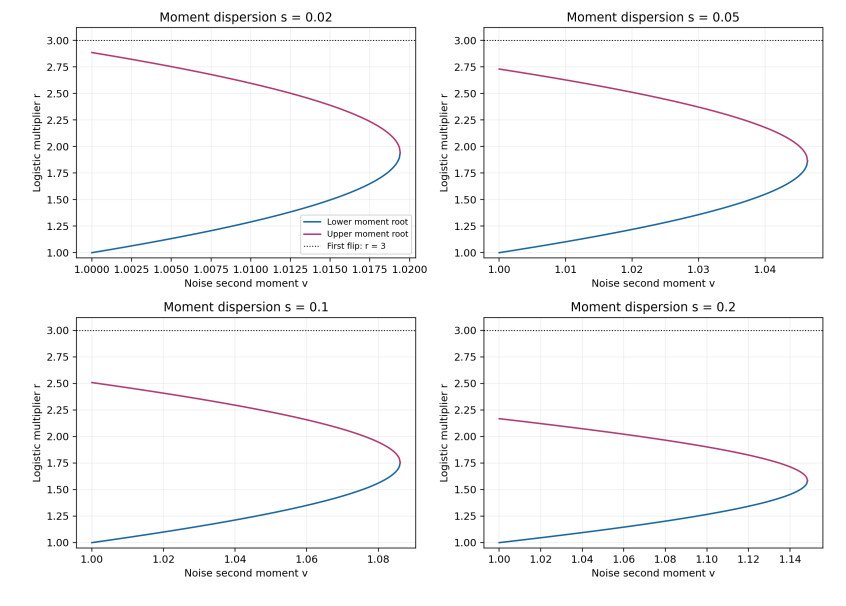
Explicit lower and upper logistic moment growth versus noise second moment, at four prescribed dispersions. The dotted line is the deterministic first-flip boundary $ r = 3 $. All nondegenerate real roots lie below this boundary
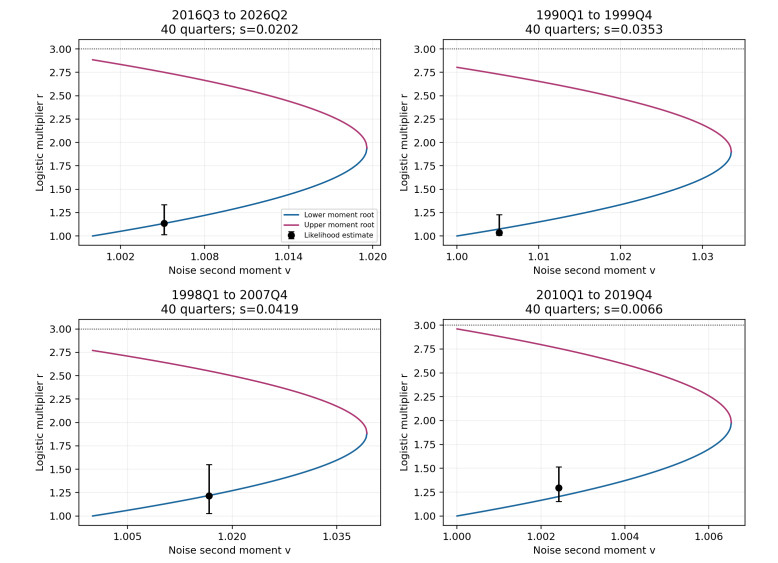
Explicit moment branches and financial likelihood estimates in four calendar-selected windows. Black points are $ (\widehat v, \widehat r) $; vertical bars show paired-bootstrap uncertainty in $ \widehat r $. The dotted horizontal reference is $ r = 3 $
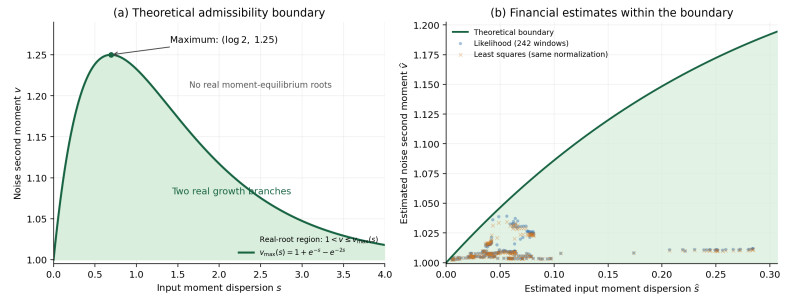
The noise admissibility boundary and financial estimates. (a) The curve $ v_{\max}(s) = 1+e^{-s}-e^{-2s} $ bounds the shaded real-root region. Its maximum is $ 5/4 $ at $ s = \log2 $. (b) Estimates $ (\widehat s, \widehat v) $ for all 242 finite-scale windows under likelihood (blue circles) and conditional-mean least squares (orange crosses), using the same normalization. Windows each contain 40 quarterly observations and overlap. All estimates lie below the boundary
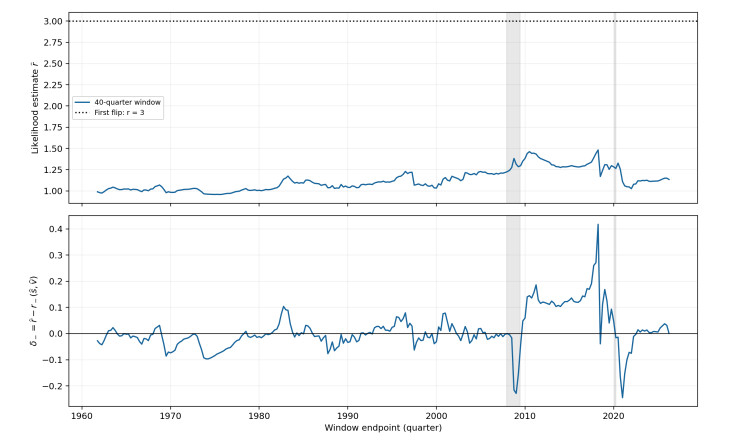
Conditional logistic likelihood estimates of $ r $ (top), and differences from the lower moment-equilibrium branch (bottom). All rolling estimates, including flagged boundary and subunit estimates, are shown. Gray bands mark the recession periods associated with the 2008 financial crisis and the 2020 COVID-19 pandemic




 DownLoad: