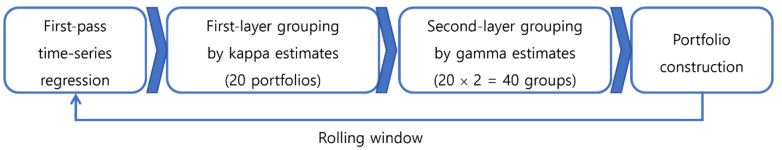
In the contemporary economy, carbon-intensive multinational corporations must function as portfolio managers, balancing growth against non-diversifiable systematic carbon risk driven by globally synchronized policies like the Paris Agreement. Analyzing 181 jurisdictions from 1985–2024, I employed a double-index model to isolate carbon beta (a distinct climate transition sensitivity) from traditional market risk through hierarchical grouping and rolling window optimization. The findings demonstrated that risk-adjusted returns could be significantly enhanced by concentrating capital (half of the total portfolio weight) within the three sorted groups exhibiting the lowest systematic risk. Notably, the 2015 Paris Agreement acted as a structural pivot, shifting optimal strategies toward defensive concentration in low-carbon regions to mitigate regulatory volatility. Sensitivity analysis further revealed that the opportunity cost of ignoring carbon risk was highest during periods of low carbon-index volatility, providing a robust, analytically grounded framework for constructing resilient business portfolios in a carbon-constrained world.
Citation: Ick Jin. Incorporating systematic carbon risk into global business portfolios for carbon-intensive industries[J]. Data Science in Finance and Economics, 2026, 6(3): 425-451. doi: 10.3934/DSFE.2026015
In the contemporary economy, carbon-intensive multinational corporations must function as portfolio managers, balancing growth against non-diversifiable systematic carbon risk driven by globally synchronized policies like the Paris Agreement. Analyzing 181 jurisdictions from 1985–2024, I employed a double-index model to isolate carbon beta (a distinct climate transition sensitivity) from traditional market risk through hierarchical grouping and rolling window optimization. The findings demonstrated that risk-adjusted returns could be significantly enhanced by concentrating capital (half of the total portfolio weight) within the three sorted groups exhibiting the lowest systematic risk. Notably, the 2015 Paris Agreement acted as a structural pivot, shifting optimal strategies toward defensive concentration in low-carbon regions to mitigate regulatory volatility. Sensitivity analysis further revealed that the opportunity cost of ignoring carbon risk was highest during periods of low carbon-index volatility, providing a robust, analytically grounded framework for constructing resilient business portfolios in a carbon-constrained world.

| [1] |
Alessandrini F, Jondeau E (2021) Optimal Strategies for ESG Portfolios. J Portf Manag 47: 114–138. https://doi.org/10.3905/jpm.2021.1.241 doi: 10.3905/jpm.2021.1.241

|
| [2] |
Andersson M, Bolton P, Samama F (2016) Hedging Climate Risk. Financ Anal J 72: 13–32. https://doi.org/10.2469/faj.v72.n3.4 doi: 10.2469/faj.v72.n3.4
|
| [3] |
Bolton P, Kacperczyk M (2021) Do investors care about carbon risk? J Financ Econ 142: 517–549. https://doi.org/10.1016/j.jfineco.2021.05.008 doi: 10.1016/j.jfineco.2021.05.008
|
| [4] |
Bos K, Gupta J (2019) Stranded assets and stranded resources: Implications for climate change mitigation and global sustainable development. Energy Res Soc Sci 56: 101215. https://doi.org/10.1016/j.erss.2019.05.025 doi: 10.1016/j.erss.2019.05.025
|
| [5] |
Buckley PJ, Casson M (2020) The Internalization Theory of the Multinational Enterprise: Past, Present and Future. Br J Manag 31: 239–252. https://doi.org/10.1111/1467-8551.12344 doi: 10.1111/1467-8551.12344
|
| [6] |
Busch T, Bauer R, Orlitzky M (2016) Sustainable Development and Financial Markets: Old Paths and New Avenues. Bus Soc 55: 303–329. https://doi.org/10.1177/0007650315570701 doi: 10.1177/0007650315570701
|
| [7] |
Ceci C, Bufalo M, Orlando G (2024) Modelling the industrial production of electric and gas utilities through the CIR3 model. Math Financ Econ 18: 1–25. https://doi.org/10.1007/s11579-023-00350-y doi: 10.1007/s11579-023-00350-y
|
| [8] |
Cesarone F, Cesetti R, Orlando G, et al. (2022) Comparing SSD-Efficient Portfolios with a Skewed Reference Distribution. Mathematics 11: 50. https://doi.org/10.3390/math11010050 doi: 10.3390/math11010050
|
| [9] |
Elton EJ, Gruber MJ (1997) Modern portfolio theory, 1950 to date. J Bank Financ 21: 1743–1759. https://doi.org/10.1016/S0378-4266(97)00048-4 doi: 10.1016/S0378-4266(97)00048-4
|
| [10] |
Elton EJ, Gruber MJ, Padberg MW (1976) Simple Criteria for Optimal Portfolio Selection. J Financ 31: 1341–1357. https://doi.org/10.2307/2326684 doi: 10.2307/2326684
|
| [11] |
Elton EJ, Gruber MJ, Padberg MW (1978) Simple Criteria for Optimal Portfolio Selection: Tracing Out the Efficient Frontier. J Financ 33: 296–302. https://doi.org/10.2307/2326371 doi: 10.2307/2326371
|
| [12] |
Engle RF, Giglio S, Kelly BT, et al. (2020) Hedging Climate Change News. Rev Financ Stud 33: 1184–1216. https://doi.org/10.1093/rfs/hhz072 doi: 10.1093/rfs/hhz072
|
| [13] |
Fama EF, MacBeth JD (1973) Risk, Return, and Equilibrium: Empirical Tests. J Polit Econ 81: 607–636. https://doi.org/10.1086/260061 doi: 10.1086/260061
|
| [14] |
Giunta N, Orlando G, Carleo A, et al. (2024) Exploring Entropy-Based Portfolio Strategies: Empirical Analysis and Cryptocurrency Impact. Risks 12: 78. https://doi.org/10.3390/risks12050078 doi: 10.3390/risks12050078
|
| [15] | Görgen M, Jacob A, Nerlinger M, et al. (2020) Carbon Risk. Working Paper, University of Augsburg. https://doi.org/10.2139/ssrn.2930897 |
| [16] |
Gu GW, Hale G (2023) Climate risks and FDI. J Int Econ 146: 103731. https://doi.org/10.1016/j.jinteco.2023.103731 doi: 10.1016/j.jinteco.2023.103731
|
| [17] |
Hsu PH, Li K, Tsou CY (2023) The Pollution Premium. J Financ 78: 1343–1392. https://doi.org/10.1111/jofi.13217 doi: 10.1111/jofi.13217
|
| [18] |
Ilhan E, Sautner Z, Vilkov G (2021) Carbon tail risk. Rev Financ Stud 34: 1540–1571. https://doi.org/10.1093/rfs/hhaa071 doi: 10.1093/rfs/hhaa071
|
| [19] | Jensen MC, Black F, Scholes MS (2006) The Capital Asset Pricing Model: Some Empirical Tests, In: Jensen MC (Ed.), Studies in the Theory of Capital Markets, New York: Praeger. https://doi.org/10.2139/ssrn.908569 |
| [20] |
Jin I (2018) Is ESG a systematic risk factor for US equity mutual funds? J Sustain Financ Invest 8: 72–93. https://doi.org/10.1080/20430795.2017.1395251 doi: 10.1080/20430795.2017.1395251
|
| [21] |
Jin I (2022a) ESG-screening and factor-risk-adjusted performance: The concentration level of screening does matter. J Sustain Financ Invest 12: 1125–1145. https://doi.org/10.1080/20430795.2020.1837501 doi: 10.1080/20430795.2020.1837501
|
| [22] |
Jin I (2022b) Systematic ESG Risk and Decision Criteria for Optimal Portfolio Selection. J Portf Manag 48: 206–225. https://doi.org/10.3905/jpm.2022.1.418 doi: 10.3905/jpm.2022.1.418
|
| [23] |
Jin I (2022c) Systematic ESG risk and passive ESG investing. J Portf Manag 48: 71–86. https://doi.org/10.3905/jpm.2022.1.344 doi: 10.3905/jpm.2022.1.344
|
| [24] |
Jin I (2024) Systematic ESG risk and hedge fund. Quant Financ Econ 8: 387–409. https://doi.org/10.3934/QFE.2024015 doi: 10.3934/QFE.2024015
|
| [25] |
Li X, Gallagher KP (2022) Assessing the climate change exposure of foreign direct investment. Nat Commun 13: 1451. https://doi.org/10.1038/s41467-022-28995-1 doi: 10.1038/s41467-022-28995-1
|
| [26] |
Madhavan A, Sobczyk A, Ang A (2021) Toward ESG Alpha: Analyzing ESG Exposures through a Factor Lens. Financ Anal J 77: 69–88. https://doi.org/10.1080/0015198X.2020.1816366 doi: 10.1080/0015198X.2020.1816366
|
| [27] |
Markowitz H (1952) Portfolio Selection. J Finance 7: 77–91. https://doi.org/10.2307/2975974 doi: 10.2307/2975974
|
| [28] |
Matsumura EM, Prakash R, Vera-Muñoz SC (2014) Firm-Value Effects of Carbon Emissions and Carbon Disclosures. Account Rev 89: 695–724. https://doi.org/10.2308/accr-50629 doi: 10.2308/accr-50629
|
| [29] | Roncalli T, Le Guenedal T, Lepetit F, et al. (2020) Measuring and Managing Carbon Risk in Investment Portfolios. Amundi Working Paper. https://doi.org/10.2139/ssrn.3681266 |
| [30] | Somers J (2022) Technologies to decarbonise the EU steel industry. JRC Technical Report EUR 30982 EN, Publications Office of the European Union. https://doi.org/10.2760/069150 |
| [31] | Task Force on Climate-related Financial Disclosures (2017) Final Report: Recommendations of the Task Force on Climate-related Financial Disclosures. Basel: Financial Stability Board. |
| [32] |
Vogl V, Åhman M, Nilsson LJ (2018) Assessment of hydrogen direct reduction for fossil-free steelmaking. J Clean Prod 203: 736–745. https://doi.org/10.1016/j.jclepro.2018.08.279 doi: 10.1016/j.jclepro.2018.08.279
|
| [33] |
Zhang H (2024) Limitations and Critique of Modern Portfolio Theory: A Comprehensive Literature Review. Adv Econ Manag Polit Sci 60: 24–29. https://doi.org/10.54254/2754-1169/60/20231190 doi: 10.54254/2754-1169/60/20231190
|
 DSFE-06-03-015-s001.pdf |
 |
Figures(6) / Tables(6)
Ick Jin. Incorporating systematic carbon risk into global business portfolios for carbon-intensive industries[J]. Data Science in Finance and Economics, 2026, 6(3): 425-451. doi: 10.3934/DSFE.2026015



 DownLoad: